What Every Lowcountry Homeowner Should Know
A few years ago, it seemed like everyone was getting a brand-new roof.
If you live throughout the Lowcountry in South Carolina—especially in Sun City and the surrounding neighborhoods—you probably remember the endless parade of roofing companies knocking on doors after storms. Yard signs appeared overnight. Neighbors compared insurance adjusters. Conversations at community events centered around who had qualified for a new roof and who was still waiting for approval.
For many homeowners, it seemed almost unbelievable. People who had never noticed a leak or a missing shingle were suddenly being told they had enough hail damage to qualify for a complete roof replacement. Some contractors assured homeowners that insurance would pay for everything. Others created a sense of urgency, suggesting that if they didn’t file a claim immediately, they might miss their chance.
It’s easy to understand why so many people said yes.
After all, replacing a roof is one of the largest expenses a homeowner will ever face. If someone tells you your insurance company is willing to pay for it, why wouldn’t you at least listen?
The truth is that homeowners insurance absolutely can pay for a new roof—but only under the right circumstances. Understanding when a roof replacement is legitimately covered, and knowing how to recognize the difference between honest guidance and an aggressive sales pitch, can protect both your home and your financial future.
What Homeowners Insurance Is Really Designed to Do
One of the biggest misconceptions we encounter is the belief that homeowners insurance exists to replace old roofs. It doesn’t.
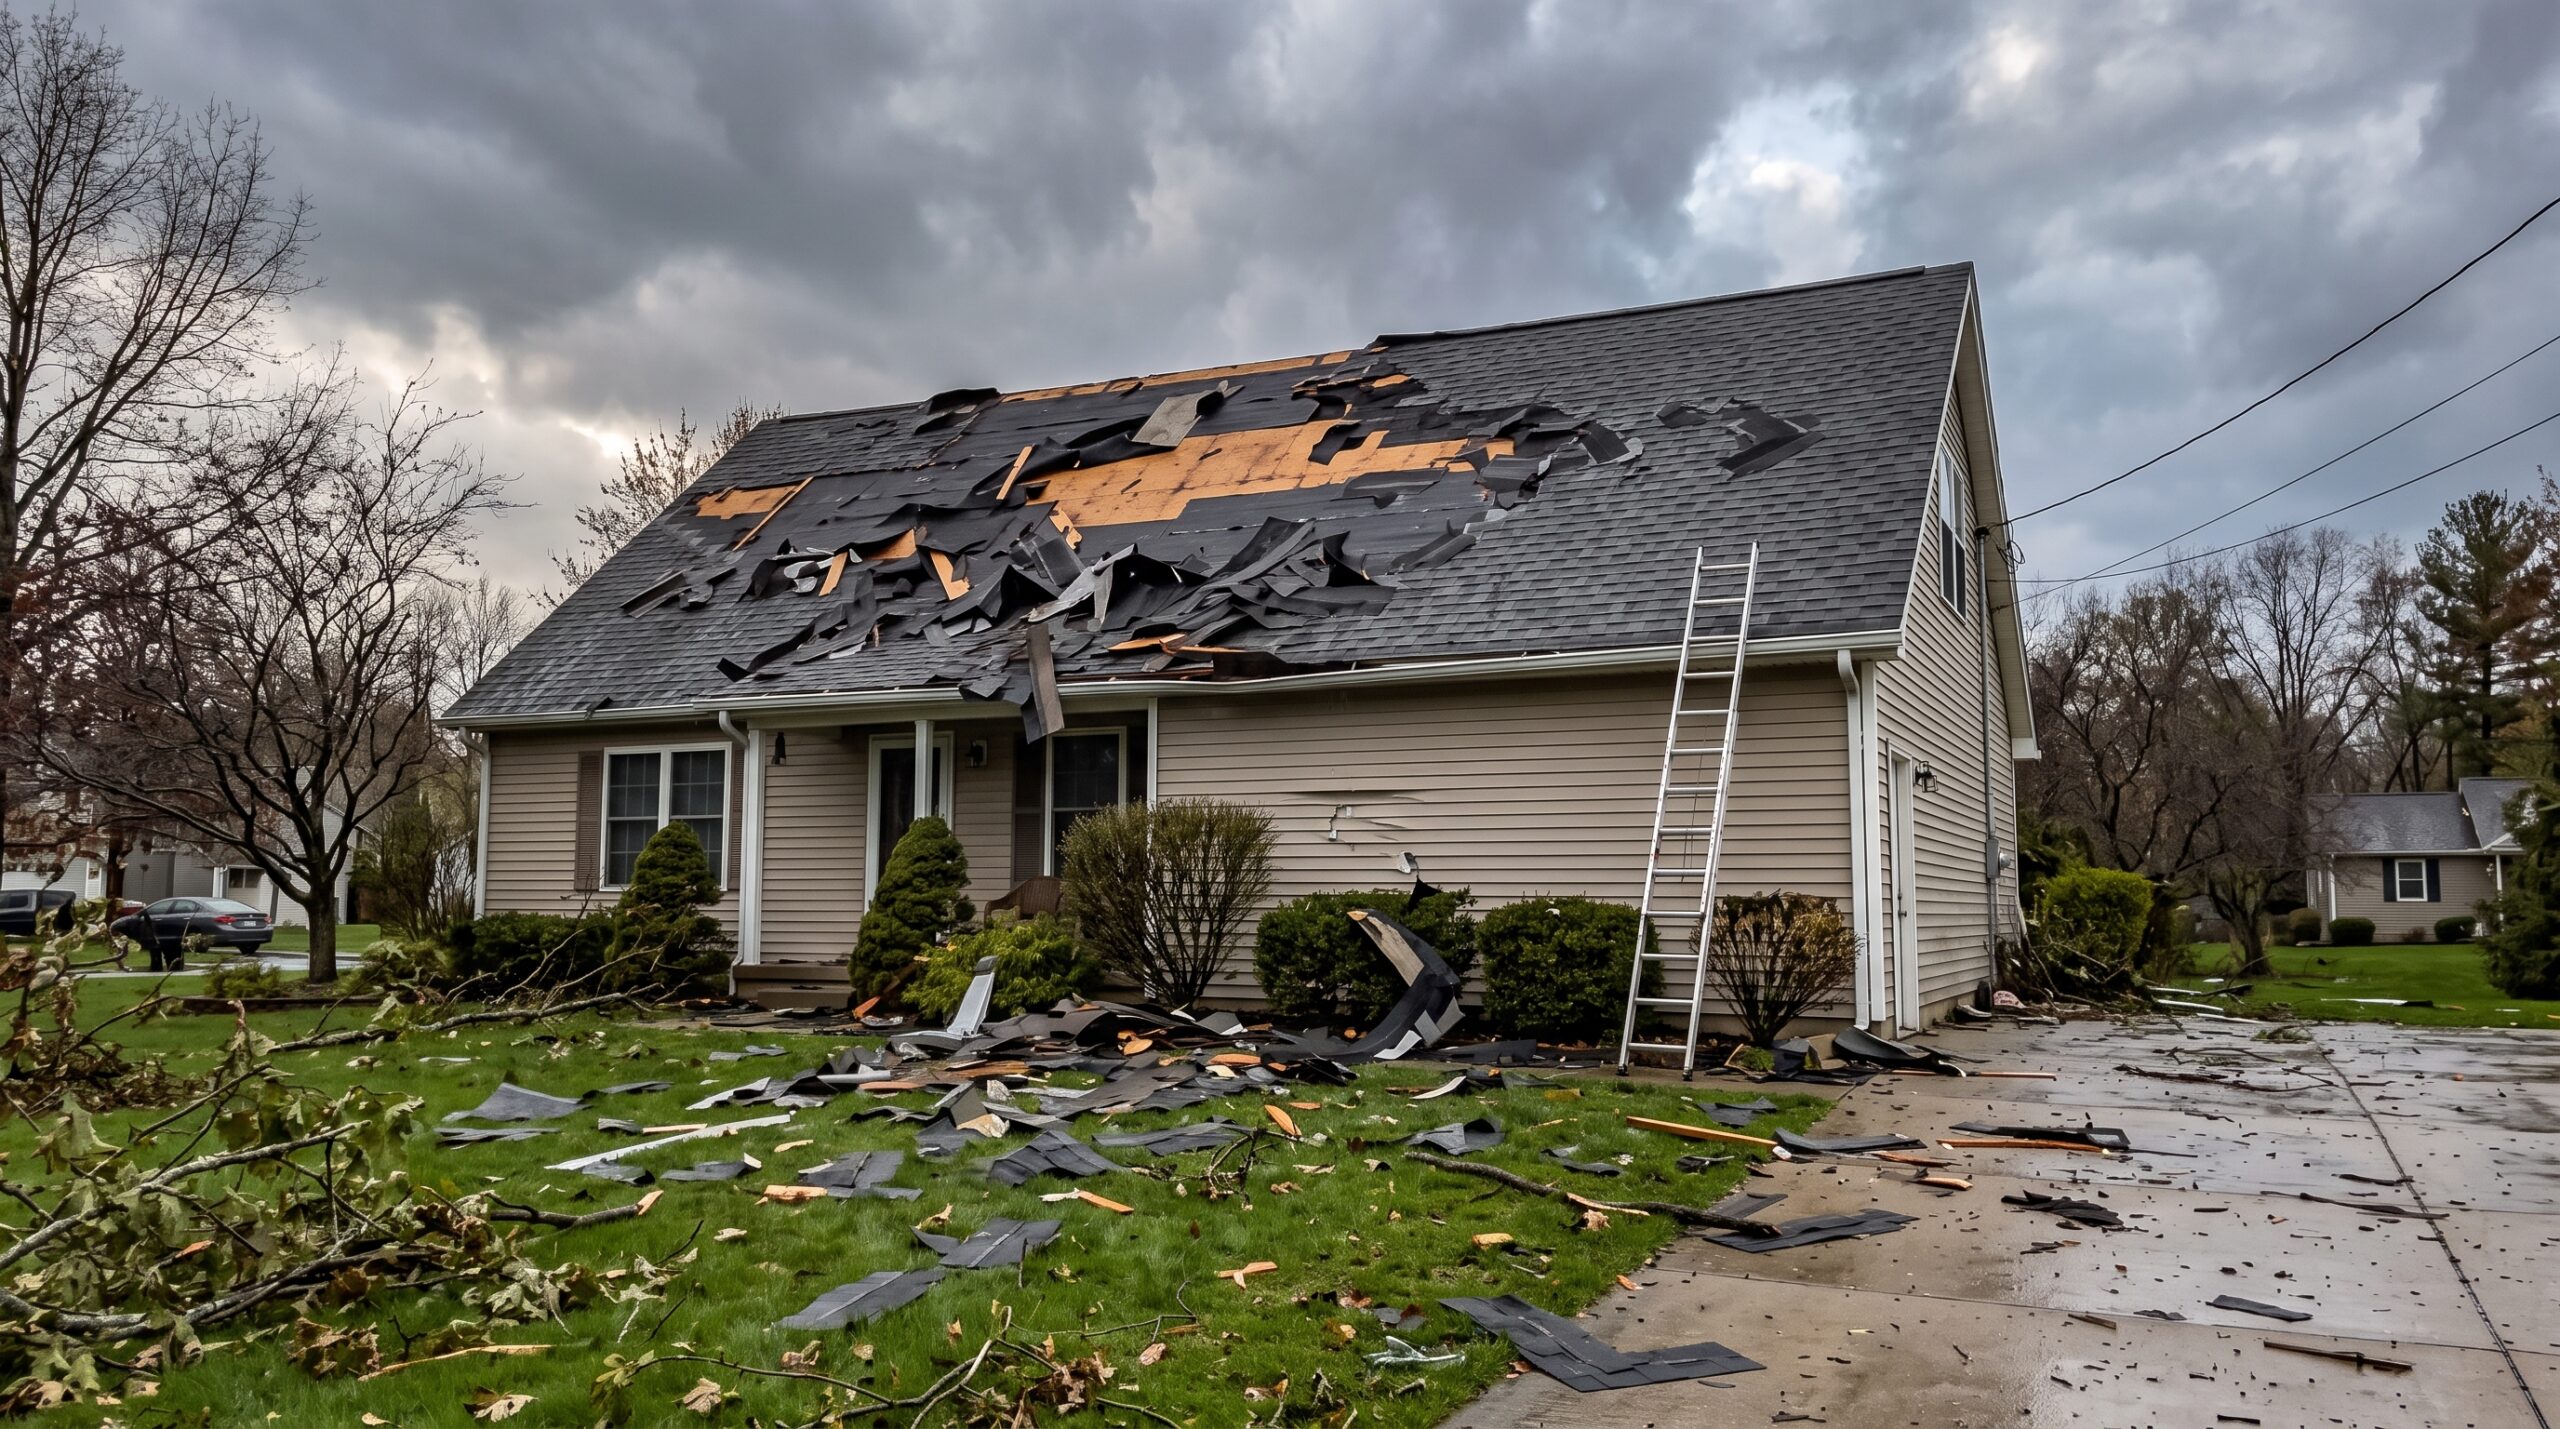
Insurance is designed to restore your home after a sudden, unexpected event. If your roof is damaged by high winds, hail, a hurricane, a fallen tree, or another covered event, your policy may help pay for repairs or, in some cases, a full roof replacement.
That’s very different from a roof that has simply reached the end of its useful life. Roofing materials naturally wear over time. Years of sunlight, humidity, heavy rain, and seasonal weather gradually take their toll. Those are expected maintenance issues, not insurance claims.
The distinction matters because a reputable roofing contractor should never begin with the assumption that your insurance company owes you a new roof. They should begin with a careful inspection and an honest assessment of what they find.
Why Did So Many Roofs Get Replaced?
It’s a fair question, and one that homeowners throughout the Lowcountry still ask today.
After major storms, many roofing companies travel into affected areas looking for work. Some are established, reputable contractors with years of experience helping homeowners recover from legitimate storm damage. Others are temporary companies that follow severe weather from state to state, hoping to generate as many insurance claims as possible before moving on to the next community.
Unfortunately, a small number of contractors built their sales strategy around convincing homeowners that almost every roof qualified for replacement. Instead of inspecting first and advising second, the sales pitch often came before the inspection.
Homeowners were told that because several neighbors had received new roofs, theirs probably qualified as well. Some were encouraged to sign contracts before their insurance company had even evaluated the property. Others were assured that the contractor would “handle everything” and that the homeowner didn’t need to worry about the details.
While many of those roofs undoubtedly had legitimate storm damage, others may not have met the standards required for an insurance claim. That distinction is important because insurance is intended to cover actual damage—not simply provide an opportunity for a free upgrade.
The Hidden Cost of a “Free Roof”
The phrase “free roof” sounds appealing, but it also creates a misunderstanding about how insurance works.
When an insurance company pays a claim, the money doesn’t come from a separate account reserved for roof replacements. Claims are paid from premiums collected from policyholders. As claims increase, insurance companies adjust premiums, deductibles, underwriting guidelines, and coverage requirements to offset those costs.
The result affects far more than the individual homeowner who filed the claim.
Many homeowners throughout South Carolina have experienced rising insurance premiums, stricter inspections, higher deductibles, and fewer carrier options in recent years. Those changes are influenced by many factors, including hurricanes, construction costs, inflation, and overall claim activity.
That’s why filing an insurance claim should never be viewed as an opportunity to receive a new roof. It should only happen when there is legitimate, documented damage that falls within the coverage of your policy.
Not Every Insurance Claim Is the Right Decision
One of the things that surprises many homeowners is learning that filing an insurance claim—even if it’s ultimately denied—can become part of your home’s insurance history.
Insurance companies maintain records of claims, and future insurers often review that history when determining premiums or whether they are willing to insure a property. While a legitimate claim should never discourage someone from using the coverage they’ve paid for, filing unnecessary claims simply because a contractor suggested it may not always be in a homeowner’s best interest.
That’s another reason why an honest inspection should always come before an insurance claim.
Sometimes the best news a homeowner can hear is that their roof is in good condition and doesn’t need to be replaced.
How Do You Know You’re Working with a Reputable Roofing Company?
Most roofing contractors are hardworking professionals who genuinely care about serving their customers. Unfortunately, like every industry, there are a few companies whose business practices have given everyone else a bad reputation.
A trustworthy roofing contractor doesn’t begin the conversation by promising you a free roof. Instead, they begin by asking questions, inspecting your roof thoroughly, documenting what they find, and explaining your options in plain language.
If storm damage is present, they’ll show you photographs, explain how the damage occurred, and help you understand the insurance process. If the damage isn’t significant enough to justify an insurance claim, they’ll tell you that as well.
Honesty may not always produce the answer a homeowner was hoping for, but it’s the foundation of every good contractor-client relationship.
Warning Signs Every Homeowner Should Recognize
Choosing the right roofing contractor often comes down to paying attention to the details.
Be cautious if someone tells you that everyone in your neighborhood qualifies for a new roof without ever climbing onto yours. Be skeptical of contractors who guarantee that your insurance company will approve a claim or who pressure you to sign paperwork before you’ve had time to understand the process.
Promises to waive deductibles, offers that sound too good to be true, or high-pressure sales tactics should all prompt homeowners to slow down and ask more questions.
A professional contractor understands that replacing a roof is a significant decision. They won’t rush you into making it.
Experience Matters
Storm damage can be complicated. Wind, hail, age, previous repairs, installation methods, and normal weathering all affect how a roof performs and how an insurance company evaluates a claim.
That’s why experience matters.
As a GAF Certified roofing contractor, Reliable Roofing Pros follows industry best practices and manufacturer installation standards. More importantly, we believe our responsibility is to provide homeowners with honest information—not simply the answer they hope to hear.
If your roof has sustained legitimate storm damage, we’ll document what we find, explain the condition of your roof, and help you navigate the insurance process with confidence.
If your roof doesn’t qualify for an insurance claim, we’ll explain that, too.
Our reputation is built on helping homeowners make informed decisions, not pressured ones.
Trust Is the Most Valuable Thing We Can Offer
Replacing a roof is a major investment, whether insurance is involved or not.
The contractor you choose should be someone who values honesty over sales quotas, education over pressure, and long-term relationships over short-term profits. A trustworthy roofing company understands that earning your confidence today is far more important than making a quick sale.
That’s the approach we’ve always believed in, and it’s the reason homeowners throughout the Lowcountry continue to trust Reliable Roofing Pros with one of their home’s most important investments.
About Reliable Roofing Pros
Reliable Roofing Pros is a locally owned, GAF Certified roofing company specializing in residential roof replacement, roof repair, storm damage restoration, metal roofing, and architectural shingle installation throughout the Lowcountry in South Carolina, including Sun City, Bluffton, Hilton Head Island, Okatie, Beaufort, Hardeeville, Ridgeland, and surrounding communities.
We believe homeowners deserve honest advice, exceptional craftsmanship, and roofing systems built to protect what matters most. Whether you need a simple repair, help after a storm, or a complete roof replacement, our experienced team is committed to providing trustworthy recommendations and quality workmanship every step of the way.
Call Reliable Roofing Pros today at 843-575-1686 to schedule your roof inspection or request your free estimate.